Currently Empty: $0.00


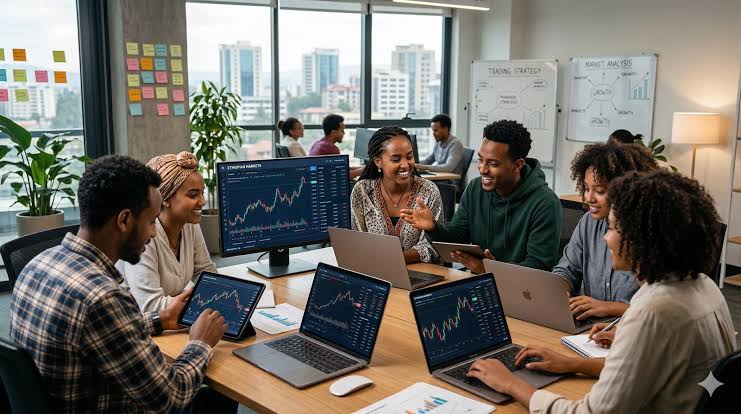
FinTech, short for Financial Technology, refers to the use of modern technology to deliver, improve, and transform financial services. It combines finance with technologies such as artificial intelligence (AI), mobile applications, cloud computing, blockchain, big data, biometrics, and automation.
Over the past decade, FinTech has changed the way individuals, businesses, banks, and other financial institutions manage money. Customers can now make payments, transfer funds, apply for loans, invest, save, and access financial information through digital platforms without always visiting a traditional bank branch.
What Is FinTech?
FinTech is a broad term covering technology-driven innovations across the financial sector. It includes:
- Mobile and digital banking
- Mobile money and digital payments
- Online lending and digital credit
- Digital wallets
- Cryptocurrency and blockchain
- Artificial intelligence and machine learning
- Automated investment platforms
- InsurTech
- RegTech and compliance technology
- Financial data analytics
- Digital identity and biometric authentication
- Open banking and API-based financial services
The objective is generally to make financial services faster, more accessible, convenient, efficient, and data-driven.
How FinTech Is Changing Traditional Banking
1. Banking Is Becoming More Digital
Traditional banking relied heavily on physical branches. Customers often had to visit a bank to open accounts, transfer money, make payments, or obtain certain services.
FinTech has accelerated the movement toward digital banking, allowing customers to perform many banking activities through smartphones and computers.
Mobile banking applications can provide services such as:
- Account management
- Fund transfers
- Bill payments
- Balance enquiries
- Digital statements
- Online account opening
- Customer support
This has changed customer expectations. People increasingly expect banking services to be available 24 hours a day, from almost anywhere.
2. Mobile Money and Digital Payments
One of the most significant FinTech developments has been the growth of digital payments.
Mobile money allows users to send and receive funds, pay bills, purchase goods and services, and perform other transactions using mobile devices.
In markets such as Ghana and other parts of Africa, mobile money has become an important component of the financial ecosystem. It has also helped expand access to financial services for people who may not have easy access to traditional bank branches.
FinTech therefore plays an important role in financial inclusion.
3. Artificial Intelligence Is Transforming Banking
Artificial intelligence is increasingly being used by financial institutions to analyze information and automate processes.
Banks and FinTech companies can use AI for:
- Fraud detection
- Customer service chatbots
- Credit assessment
- Transaction monitoring
- Personalized financial recommendations
- Risk analysis
- Anti-money laundering monitoring
- Predictive analytics
For example, an AI system can analyze transaction patterns and identify activity that appears unusual. This can help financial institutions investigate potentially fraudulent transactions more quickly.
AI is also changing customer service by allowing institutions to provide automated responses to common customer questions.
4. Banking Is Becoming More Personalized
Traditional banking products were often designed for broad customer categories.
FinTech makes it easier to use customer data to develop more personalized financial services.
For example, digital platforms can analyze a customer’s transaction history and financial behavior to provide customized:
- Savings recommendations
- Investment information
- Loan offers
- Spending insights
- Financial alerts
This movement toward personalization can improve the customer experience while allowing financial institutions to better understand their customers.
5. FinTech Is Changing Lending
Technology has also transformed the lending process.
Traditional loan applications may require significant documentation and several visits to a bank. Digital lending platforms can automate parts of the application, verification, credit assessment, and approval processes.
Alternative data and automated analytics may also help lenders assess customers who have limited traditional credit histories.
However, digital lending must be properly regulated. Fast access to credit can create risks if customers are given loans without adequate affordability and credit assessments.
6. Blockchain and Cryptocurrency
Blockchain is another important FinTech technology.
A blockchain is a distributed digital ledger that can record transactions across a network. It has applications beyond cryptocurrency, including areas such as:
- Cross-border payments
- Digital identity
- Trade finance
- Asset tokenization
- Record keeping
- Smart contracts
Cryptocurrencies such as Bitcoin have also challenged traditional ideas about money and financial intermediaries.
Banks and regulators continue to study blockchain and digital assets to understand their potential benefits, risks, and appropriate regulatory frameworks.
7. Open Banking and APIs
FinTech is also changing the way financial institutions exchange information.
Open banking allows authorized third-party financial service providers to access certain financial information or initiate services through secure application programming interfaces (APIs), subject to applicable rules and customer permissions.
This can allow customers to connect different financial services through a single digital ecosystem.
For example, a customer could potentially use one application to view information from multiple financial accounts.
Open banking can encourage competition and innovation, but it also makes data protection, cybersecurity, authentication, and customer consent extremely important.
FinTech and Financial Inclusion
One of FinTech’s most important contributions is its potential to expand access to financial services.
People living far from bank branches can use mobile phones and digital platforms to access financial services.
Small businesses can also benefit from:
- Digital payments
- Online banking
- Digital bookkeeping
- Electronic invoicing
- Digital credit
- Online investment services
In developing economies, these technologies can help connect previously underserved populations to the formal financial system.
The Rise of the Digital Bank
FinTech has also contributed to the emergence of digital-first banking models.
Unlike traditional banks, which typically have extensive physical branch networks, digital banks can deliver many services primarily through websites and mobile applications.
The distinction between a traditional bank and a FinTech company is also becoming less clear. Banks are adopting FinTech solutions, while technology companies and FinTech firms are increasingly providing financial products.
The future financial ecosystem is therefore likely to involve greater collaboration between banks, FinTech companies, telecommunications companies, technology providers, payment companies, and regulators.
Challenges and Risks of FinTech
Despite its benefits, FinTech also creates significant challenges.
Cybersecurity
As more financial services move online, cybercriminals have more opportunities to target financial systems and customers.
Banks and FinTech companies must invest heavily in cybersecurity, authentication, encryption, monitoring, and incident response.
Data Privacy
FinTech depends heavily on data. This creates important questions about how customer information is collected, stored, shared, and used.
Financial institutions must protect customer data and comply with applicable data protection requirements.
Fraud
Digital platforms can be targeted by criminals through identity theft, phishing, account takeover, social engineering, and other forms of fraud.
Customer education and strong security controls are therefore essential.
Regulatory Compliance
Financial institutions must comply with regulations covering areas such as:
- Anti-Money Laundering (AML)
- Counter-Terrorist Financing (CTF)
- Know Your Customer (KYC)
- Consumer protection
- Data protection
- Cybersecurity
- Payment systems
- Financial reporting
The growth of FinTech means regulators must continually adapt their frameworks to address new technologies and business models.
The Future of FinTech and Banking
The relationship between technology and banking will continue to evolve.
Future developments are likely to include greater use of:
Artificial Intelligence → smarter automation and financial analysis
Mobile Technology → increasingly accessible financial services
Cloud Computing → scalable banking infrastructure
Blockchain → new approaches to payments, identity, and financial records
Biometrics → stronger identity verification
Data Analytics → more personalized financial services
Digital Payments → faster and increasingly integrated transactions
RegTech → technology-assisted regulatory compliance and monitoring
The future bank may therefore be less defined by physical branches and more by its digital platforms, data capabilities, security infrastructure, and ability to deliver financial services seamlessly.
Conclusion
FinTech is more than simply using computers or mobile phones for banking. It represents a fundamental transformation in how financial services are designed, delivered, monitored, and consumed.
From mobile money and digital payments to artificial intelligence, blockchain, digital lending, and open banking, technology is changing the relationship between financial institutions and their customers.
For banks and financial professionals, understanding FinTech is becoming increasingly important. The financial sector of the future will require professionals who understand not only banking and finance, but also technology, data, cybersecurity, digital payments, artificial intelligence, risk management, and regulatory compliance.
FinTech is therefore not replacing banking—it is reshaping what banking means in the digital age.